- Free Consultation 24/7: (800) 337-7755 Tap Here to Call Us


How a Florida Life Insurance Claim Works for Beneficiaries


Updated November 2026
A Florida life insurance claim is a request by the named beneficiary to receive the death benefit after the insured person dies. The beneficiary usually files a claim form with the insurer, along with a certified death certificate. The insurer then reviews the policy and the cause of death before approving, delaying or denying payment.
If your life insurance claim has been delayed, disputed or denied, the Law Offices of Jason Turchin may be able to help. Call 800-337-7755 for a free consultation.
Florida Life Insurance Claims at a Glance
| Question | Short answer |
|---|---|
| Who can file a life insurance claim? | Usually the beneficiary named on the policy. If no beneficiary survives, the benefit may go to contingent beneficiaries or the insured’s estate. |
| What do I need to file? | Typically a completed claim form, a certified death certificate, the policy number and proof of your identity. |
| How long does payment take? | Many claims are paid within weeks of a complete filing. Missing documents, contestability reviews or competing claims can cause delays. |
| Does life insurance pay for a suicidal death? | Often yes, if the policy’s suicide exclusion period has passed. Many policies exclude suicide during the first two years. |
| Can an insurer deny a claim? | Yes. Common reasons include a lapsed policy, an excluded cause of death or alleged misstatements on the application. |
What Is a Life Insurance Claim?
A life insurance claim is the formal request a beneficiary makes to collect the death benefit from a policy after the insured person dies. Life insurance is a contract, and the claim starts the insurer’s review of whether that contract requires payment.
If the insurer approves the claim, it pays the agreed amount to the designated beneficiaries. Payment may be a lump sum, an annuity or another method allowed by the policy. To learn more about how policy terms affect payment, see our guide to understanding your Florida life insurance policy.
What Types of Life Insurance Pay a Death Benefit?
The two main types are term life insurance and whole life insurance. Both pay a death benefit, but they differ in how long coverage lasts and whether the policy builds cash value.
| Feature | Term life insurance | Whole life insurance |
|---|---|---|
| Length of coverage | A set period, often 10, 20 or 30 years | The insured’s entire lifetime |
| Death benefit | Paid if the insured dies during the term | Paid whenever the insured dies, if the policy is in force |
| Cash value | Usually none. The policy may expire without value | Usually builds cash value that may be borrowed against or cashed in |
Many people also have group life insurance through an employer. Those claims may be governed by federal law instead of Florida law. Read more about ERISA life insurance claims and how they can differ from individual policies.
How Do You File a Florida Life Insurance Claim?
To file a Florida life insurance claim, the beneficiary usually contacts the insurer, completes its claim form and submits a certified death certificate. The process is similar with most insurers, including large companies such as John Hancock.
- Obtain the death certificate. A certified copy is usually required to prove the death. Copies can often be obtained from the funeral home or the vital records office. Here is how to obtain a death certificate in Florida.
- Contact the insurance company. Notify the insurer’s claims department of the death and request a claim form. Have the policy number ready if you can find it.
- Complete and submit the claim form. The form asks for personal information and policy details. Attach the death certificate and any other documents the insurer requests.
- Wait for the insurer’s review. The insurer may verify that the policy was in force and confirm the cause of death. It may ask for medical records or other information.
- Receive the death benefit. If the claim is approved, the benefit is paid by lump sum, annuity or another method allowed by the policy.
Before you file, it helps to gather these items:
- Policy documents. The policy itself, the policy number and any recent statements.
- Certified death certificate. Request several copies, since other institutions may need them too.
- Your identification. A government-issued ID and your contact information.
- Proof of relationship. Documents such as a marriage or birth certificate, if the insurer asks.
- Correspondence log. Notes on every call, letter and email with the insurer.
For a step-by-step look at filing and appealing in South Florida, see filing a life insurance claim in Miami.
How Long Does It Take to Get Life Insurance After Death?
Many life insurance claims are paid within weeks after the insurer receives a complete claim. Claims can take longer if documents are missing, the death occurred within the contestability period or more than one person claims the benefit.
Florida law may require insurers to pay interest on death benefits in some situations. Learn more about interest payments on life insurance proceeds and read our post on how long a life insurance claim takes to pay out.
How Long After Death Do You Have to Collect Life Insurance?
Many life insurance policies do not set a short deadline for beneficiaries to file a death claim, but the policy terms control. Filing promptly is generally wise, because delays can make records harder to find and can slow payment.
Read the policy for any notice or proof of loss requirements. If a benefit goes unclaimed for a long time, it may eventually be reported to the state as unclaimed property.
Does Life Insurance Pay for a Suicidal Death?
Life insurance often does pay for a suicidal death once the policy’s suicide exclusion period has passed. Many policies exclude suicide during the first two years after the policy is issued, and the insurer may refund premiums instead of paying the benefit during that time.
The exact terms depend on the policy wording and the law that applies. Rules in other states, such as Texas or Ohio, may differ, so the policy and the governing state law should be reviewed together. If a claim is denied based on a suicide clause, an attorney can review whether the exclusion actually applies.
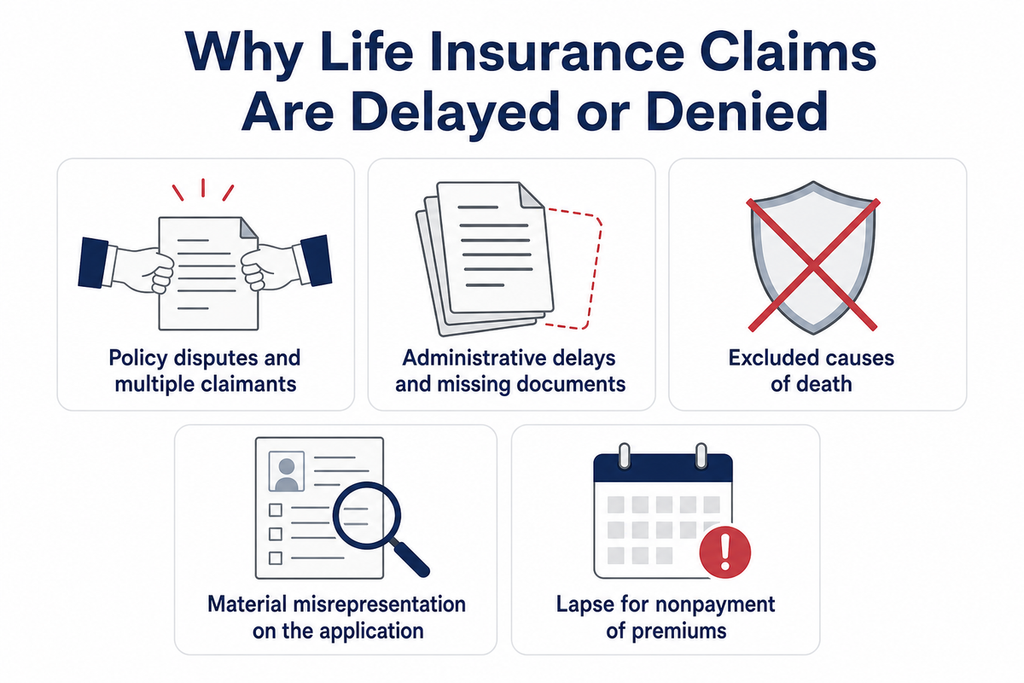
Why Are Life Insurance Claims Delayed or Denied?
Life insurance claims are most often delayed or denied because of missing paperwork, a lapsed policy, an excluded cause of death or alleged misstatements on the application. Some of these reasons can be challenged.
- Policy disputes. Disagreements over policy terms, or multiple claimants after a divorce or recent beneficiary change.
- Administrative delays. Errors or missing documents that hold up payment.
- Excluded causes of death. The insurer claims the death falls under a policy exclusion.
- Material misrepresentation. The insurer claims the application contained false or incomplete information.
- Lapse for nonpayment. The insurer claims premiums were not paid and coverage ended.
Florida Statute §627.455 generally makes a life insurance policy incontestable after it has been in force during the insured’s lifetime for two years from its date of issue, except for nonpayment of premiums. That is why insurers often look more closely at deaths within the first two years.
What Happens When More Than One Person Claims the Benefit?
When two or more people claim the same death benefit, the insurer may hold payment or ask a court to decide who should be paid. This often happens after a divorce or a last-minute beneficiary change.
Under Florida Statute §732.703, a designation naming a former spouse as beneficiary may become void upon divorce in many situations, though there are exceptions. Read more about revocation upon divorce in life insurance policies.
Why Keep Beneficiary Designations Up to Date?
Current beneficiary designations help the death benefit reach the people the insured intended. If a named beneficiary has died or cannot be located, the claims process can become more complicated.
Reviewing designations after a marriage, divorce, birth or death can help prevent disputes. You can also learn about broader life insurance denials and disputes.
Why Choose the Law Offices of Jason Turchin
Attorney Jason Turchin is the founder and principal attorney of the Law Offices of Jason Turchin, based in Florida. The firm helps beneficiaries with life insurance claims, delays and denials throughout Florida.
Jason Turchin holds an Avvo 10.0 Superb Rating. He was AV Preeminent Peer Rated for Highest Level of Professional Excellence by Martindale-Hubbell in 2026. He has been on the Super Lawyers list from 2020 through 2026, and the firm has held an A+ BBB rating annually from 2014 through 2026.
The firm handles cases in Florida, New York, New Jersey and Washington, D.C., and throughout the U.S. with a network of co-counsels and local counsels. Cases are handled on a contingency fee basis, with fees and costs waived if there is no recovery.
Frequently Asked Questions About Florida Life Insurance Claims
How do I file a death claim with a company like MetLife?
Contact the insurer’s claims department, request a claim form and submit it with a certified death certificate and the policy number. Each company has its own forms, so follow the insurer’s instructions.
Can a life insurance company deny a claim after two years?
It is harder. Florida Statute §627.455 generally makes a policy incontestable after two years in force during the insured’s lifetime, except for nonpayment of premiums. Exclusions and lapse issues may still come up.
Do I need a lawyer to file a life insurance claim?
Many claims are paid without a lawyer. An attorney may help if the claim is delayed, denied or disputed by another claimant. Some people also prefer to have a lawyer assist with the claims filing process.
What should I do if my life insurance claim is denied?
Ask the insurer for the denial in writing, keep all letters and the policy, and note any appeal deadline. An attorney can review whether the denial follows the policy and the law.
Talk to a Florida Life Insurance Lawyer
If a Florida life insurance claim has been delayed or denied, you may have options. Call the Law Offices of Jason Turchin at 800-337-7755 or contact us online for a free consultation.
