- Free Consultation 24/7: (800) 337-7755 Tap Here to Call Us


Life Insurance Beneficiary Dispute After Death: Who Gets the Money?


A life insurance beneficiary dispute can turn what should be a relatively straightforward claim into a complicated legal conflict. After an insured person dies, family members may discover that more than one person claims the policy proceeds, that the beneficiary designation was changed shortly before death, or that divorce, incapacity, undue influence, fraud, or another issue may affect who should receive the money.
There is no single rule that determines every beneficiary dispute, as there are various nuances and laws which may apply. The answer may depend on the policy documents, the most recent valid beneficiary designation, state or federal law, divorce records, evidence concerning the insured’s intent, and the circumstances surrounding any beneficiary change. A general insurance lawyer may not be as familiar with life insurance issues as our life insurance lawyers who have handled hundreds of life insurance claims.
In some cases, the insurance company may place the disputed life insurance proceeds into a court registry through an interpleader lawsuit and ask the competing claimants to establish who may be legally entitled to the funds.
If you are involved in a life insurance beneficiary dispute after a loved one’s death, call 800-337-7755 or chat with our live agents to discuss your potential claim.
Who Normally Gets Life Insurance Money After Someone Dies?
Life insurance benefits are generally intended to be paid according to the policy’s valid beneficiary designation, subject to applicable law and the terms of the policy. Many claims are paid without a dispute. Problems can arise, however, when the insurer receives competing beneficiary claims or information suggesting that the designation may not be legally enforceable.
A policy may identify a primary beneficiary and one or more contingent beneficiaries. If the primary beneficiary predeceased the insured, disclaims the proceeds, or may be legally disqualified, the insurer may need to determine whether a contingent beneficiary, estate, or another claimant could be entitled to the death benefit.
The analysis can become more difficult if the insurer has multiple beneficiary forms in its records or if family members dispute how a recent change was made.
Why Do Life Insurance Beneficiary Disputes Happen?
Beneficiary disputes can arise for many reasons, and several issues may overlap in the same case. Common situations can include:
- A beneficiary designation was changed shortly before death.
- Two different beneficiary forms identify different people.
- A former spouse remains listed on the policy after divorce.
- A current spouse disputes a former spouse’s rights.
- Family members claim the insured lacked mental capacity.
- A beneficiary is accused of exerting undue influence.
- Someone alleges that a beneficiary form was forged.
- A power of attorney was used in connection with a beneficiary change.
- A court order or divorce settlement may affect beneficiary rights.
- A beneficiary died before the insured.
- The policy is connected to an employer-sponsored benefit plan.
- A claimant alleges that a state slayer statute applies.
- An estate and an individually named beneficiary both assert claims.
These disputes can involve substantial policy proceeds, and the insurance company may be reluctant to choose between competing claimants when doing so could expose it to additional liability.
Does the Person Named on the Policy Always Get the Money?
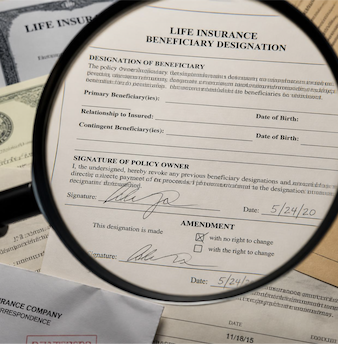
Not necessarily. A beneficiary designation can be highly important, but another claimant may have grounds to challenge whether that designation should control.
For example, a person may be listed as beneficiary on the insurer’s most recent form, but another claimant could argue that the form was forged, that the insured lacked capacity, that someone improperly influenced the insured, or that applicable law prevents the beneficiary from receiving the proceeds.
The reverse can also be true. A family member may believe a beneficiary change was unfair, but unfairness by itself may not be enough to invalidate a properly executed designation. The strength of a challenge can depend on the evidence and governing law.
What If the Beneficiary Was Changed Shortly Before Death?
A beneficiary change shortly before death often attracts scrutiny, especially if it is significantly different from the insured’s long-standing estate or insurance plan.
Consider a hypothetical example. A parent owns a $900,000 life insurance policy and names three adult children as equal beneficiaries for more than a decade. Several weeks before death, the policy is changed so that one child receives the entire death benefit.
The excluded children may question whether the parent knowingly made the change, whether the parent understood its effect, or whether the new sole beneficiary pressured the parent.
The timing of the change does not automatically make it invalid. Relevant questions may include who initiated the change, how it was submitted, whether the insured communicated an intent to make the change, and whether there was evidence of cognitive impairment or outside pressure.
Can Lack of Mental Capacity Affect a Life Insurance Beneficiary?
Potentially. A beneficiary dispute may involve allegations that the insured did not have sufficient mental capacity when a designation was changed.
These issues may arise when an insured was experiencing dementia, cognitive decline, serious illness, hospitalization, or other medical conditions near the time of the beneficiary change. Medical records can become important, but a diagnosis alone does not necessarily establish whether a particular transaction was valid.
Evidence may include physician records, testimony from caregivers or witnesses, messages from the insured, financial activity, and documentation showing how the beneficiary change was completed.
What Is Undue Influence in a Life Insurance Beneficiary Dispute?
Undue influence allegations can arise when someone claims that a beneficiary improperly pressured or manipulated the insured into changing a policy.
For example, questions may arise when a beneficiary was heavily involved in the insured’s care, controlled access to the insured, helped prepare or submit beneficiary paperwork, or received a major financial benefit from a sudden change.
That does not mean every caregiver, child, spouse, or trusted person who receives life insurance proceeds engaged in undue influence. These cases are highly fact-dependent, and the beneficiary may have evidence showing that the insured independently intended to make the change.
What If the Beneficiary Form Was Forged?
An alleged forgery can create a direct challenge to the validity of the beneficiary designation. The dispute may involve signatures, electronic submission records, insurer files, communications, witnesses, and other evidence concerning who completed or submitted the change.
Some beneficiary changes are completed electronically, which can create a different evidentiary trail than a traditional signed form. Depending on the circumstances, records concerning logins, account activity, submission dates, and communications with the insurer may become relevant.
Can a Power of Attorney Change a Life Insurance Beneficiary?
A beneficiary dispute may become more complicated when someone acting under a power of attorney participated in changing the beneficiary. The answer can depend on the authority granted by the document, applicable law, the type of policy, and the circumstances surrounding the transaction.
Questions can become particularly significant when the person using the power of attorney benefits from the change. A competing claimant may argue that the agent lacked authority, exceeded the authority granted, or otherwise acted improperly.
LifeClaims.com discusses this issue further in its resource on challenging a beneficiary change involving a power of attorney.
Who Gets Life Insurance After Divorce?
Divorce is a common source of beneficiary disputes. A former spouse may remain listed on a life insurance policy even though the insured later remarried or intended the money to go to children or another beneficiary.
The answer can depend on the policy, applicable state law, divorce judgment, marital settlement agreement, beneficiary documents, and whether federal law applies.
Some employer-sponsored policies may be governed by the Employee Retirement Income Security Act of 1974, commonly known as ERISA. Federal law can sometimes affect the analysis differently than a privately purchased policy governed primarily by state law.
Our website has more information on former spouse life insurance claims and life insurance claims and divorce.
What Happens If the Named Beneficiary Dies Before the Insured?
If a beneficiary dies before the insured, the policy terms and beneficiary designations become especially important. The insurer may look to a contingent beneficiary if one was named. If there is no surviving beneficiary, the policy may provide another method for determining where the proceeds should go.
Depending on the policy and applicable law, an estate may become involved. This is one reason beneficiary designations should be reviewed periodically, particularly after major life events such as marriage, divorce, death, or the birth of children.
Can the Estate Receive Life Insurance Proceeds?
Potentially. An insurer may pay life insurance benefits to an estate when the policy specifically names the estate or when no valid beneficiary survives, depending on the policy terms and applicable law.
When an estate becomes involved, probate and creditor issues may arise that would not typically affect proceeds paid directly to an individual beneficiary. Anyone involved in this type of dispute may want to review the policy carefully before assuming where the money should go.
Our site includes additional information about a Florida life insurance policy involving an estate.
What Is the Florida Slayer Statute?
An accusation that a beneficiary intentionally caused the insured’s death can create one of the most serious types of life insurance beneficiary disputes.
Florida law includes provisions commonly referred to as the Florida Slayer Statute. Depending on the circumstances, these provisions may prevent someone from benefiting financially from unlawfully and intentionally causing another person’s death.
If a named beneficiary may be disqualified, other parties could potentially assert claims to the proceeds. These may include contingent beneficiaries, family members, or an estate.
Our firm has a dedicated resource regarding Florida Slayer Statute life insurance claims. LifeClaims.com also provides a detailed discussion of Florida’s Slayer Statute and life insurance proceeds.
What Happens When Two Beneficiaries Both Claim the Money?
The insurance company may investigate the competing claims and request documentation from each side. If the insurer determines that it cannot safely decide who should receive the proceeds, it may file an interpleader lawsuit.
Through interpleader, the insurer may ask to deposit the life insurance proceeds with a court. The competing claimants can then present their legal arguments concerning entitlement to the funds.
This can protect the insurer from choosing between claimants while moving the underlying beneficiary dispute into litigation.
For more information about this process, see our page on life insurance interpleader actions.
What Happens in a Life Insurance Interpleader Lawsuit?
An interpleader case may involve several stages. The insurer may file a complaint naming the competing claimants, ask to deposit the policy proceeds with the court, and request discharge from further responsibility for deciding who receives the money.
After the court discharges the insurer, the remaining claimants may continue litigating over who has the right to receive the policy proceeds. The case can involve written discovery, document production, subpoenas, depositions, motions, mediation, settlement negotiations, and potentially trial.
The court may ultimately determine who should receive the proceeds, or the parties may resolve the dispute through a negotiated agreement.
Our related article explains life insurance interpleader claims in additional detail.
Can Competing Beneficiaries Split the Life Insurance Money?
Potentially. A life insurance beneficiary dispute does not always have to result in one person receiving everything and another receiving nothing.
Claimants may sometimes negotiate a settlement that divides the proceeds. Parties may consider a settlement when they face factual uncertainties, competing legal arguments, significant litigation expenses, or the prospect of extended court proceedings.
Whether a negotiated division makes sense depends on the facts of the case and the strength of each claimant’s position.
What Evidence May Decide a Beneficiary Dispute?
A beneficiary dispute can turn on documents and testimony that may not initially appear important. Potentially relevant evidence can include:
- The complete life insurance policy
- Current beneficiary designation forms
- Prior beneficiary forms
- Electronic beneficiary-change records
- Insurance company correspondence
- Insurance agent notes
- Medical records
- Emails and text messages
- Wills and trusts
- Powers of attorney
- Divorce judgments
- Marital settlement agreements
- Retirement or employer benefit documents
- Witness testimony
- Financial records
- Evidence concerning the insured’s intent
Someone involved in a beneficiary dispute should consider preserving potentially relevant documents and electronic communications. Evidence can become harder to recover as time passes.
Can You Challenge a Life Insurance Beneficiary After the Insured Dies?
Potentially. Many beneficiary disputes arise only after the insured dies, when competing parties discover who the policy names as beneficiary or learn about a recent beneficiary change.
The legal basis for a challenge can vary. A person may claim that a beneficiary change was invalid, that another designation controls, that the beneficiary is legally disqualified, or that state or federal law affects entitlement.
It can be important to act promptly because insurance claims and lawsuits may involve deadlines. A claimant may also need time to obtain documents and preserve evidence.
What Should You Do If Someone Is Disputing Your Life Insurance Benefits?
If you learn that another person is challenging your claim, consider taking several practical steps:
- Save all insurance correspondence. Keep letters, claim forms, emails, and notices from the insurer.
- Preserve beneficiary documents. Maintain copies of current and prior designations if available.
- Do not delete communications. Relevant emails, messages, and electronic records may become evidence.
- Review divorce or estate documents. These records may affect the analysis in certain disputes.
- Watch for court papers. If the insurer files interpleader, you may receive a summons and complaint requiring a response.
- Consider speaking with a life insurance lawyer. An attorney can evaluate the competing claim and discuss potential options.
Do You Need a Lawyer for a Life Insurance Beneficiary Dispute?
Not every life insurance claim requires legal representation, but a contested beneficiary dispute can involve substantial proceeds and complicated questions of insurance, contract, probate, divorce, and federal law.
If an interpleader lawsuit has already been filed, the dispute is active litigation. Claimants may need to respond to pleadings, participate in discovery, take or defend depositions, evaluate motions, negotiate, and potentially prepare for trial.
A lawyer familiar with life insurance disputes can review the policy, beneficiary history, competing claims, and available evidence and help evaluate the potential path forward.
Why Choose Jason Turchin, Esq. for a Life Insurance Beneficiary Dispute?
Jason Turchin, Esq. and his firm handle life insurance disputes involving competing beneficiaries, interpleader lawsuits, former spouses, disputed beneficiary changes, and other contested claims.
Jason has been selected to Super Lawyers each year from 2020 through 2026 and was previously selected as a Super Lawyers Rising Star in 2011 and from 2013 through 2016. He has received an Avvo 10.0 Superb Rating and was AV Preeminent Peer Rated for Highest Level of Professional Excellence by Martindale-Hubbell in 2026. The firm also received the Martindale-Hubbell Client Champion Platinum Award in 2026 and has maintained an A+ BBB rating annually from 2014 through 2026.
Jason is a member of the Million Dollar Advocates Forum list and Multi-Million Dollar Advocates Forum list. He is also a Lifetime Charter Member of Best Attorneys of America and was named to America’s Top 100 Personal Injury Attorneys® list in 2026, 7 Figure Litigators® – America’s Premier High-Stakes Trial Lawyers® in 2026, and the 2026 MyLegalWin Top Attorneys in America list.
His legal commentary and work have been featured in or on CBS Evening News, CBS This Morning, CNN, The New York Times, The Wall Street Journal, Bloomberg News, USA Today, The Washington Post, and Rolling Stone.
Ratings, awards, memberships, media appearances, and prior case results do not guarantee a similar outcome in any future matter.
Frequently Asked Questions About Life Insurance Beneficiary Disputes
Who gets life insurance if two people claim to be the beneficiary?
The answer depends on the beneficiary designations, policy terms, applicable law, and basis for each claim. The insurance company may investigate or file an interpleader lawsuit and ask a court to determine entitlement.
Can a family member challenge a life insurance beneficiary?
Potentially. A family member may assert a challenge based on issues such as an allegedly invalid beneficiary change, lack of capacity, undue influence, forgery, divorce, a power of attorney, or another legal issue. Whether the challenge may succeed depends on the facts and law.
Can a spouse override a named life insurance beneficiary?
Not automatically. A spouse’s rights can depend on the type of policy, governing law, beneficiary designation, divorce or marital documents, and whether federal law applies.
What happens if there is no living beneficiary?
The policy terms may identify what happens if no named beneficiary survives the insured. Depending on the policy and applicable law, proceeds could potentially pass to a contingent beneficiary, estate, or another recipient.
How long can a life insurance beneficiary dispute take?
There is no universal timeline. Some disputes may resolve through an early agreement, while cases involving interpleader, discovery, contested motions, or trial can take significantly longer.
Can beneficiaries agree to split the proceeds?
Potentially. Competing beneficiaries may be able to reach a negotiated settlement dividing the proceeds, depending on the circumstances and willingness of the parties.
What if the insurance company already deposited the money with the court?
You may still pursue your claim. Depositing the proceeds does not necessarily determine who gets the money. The competing claimants may still need to establish their respective rights before the court distributes the funds.
Talk to a Life Insurance Beneficiary Dispute Lawyer
If someone is challenging your rights to life insurance proceeds, or if you believe a beneficiary designation should not control, the attorneys at Jason Turchin, Esq. can review the policy, beneficiary history, and circumstances surrounding the dispute and discuss potential options.
Our firm handles cases involving competing beneficiaries, interpleader lawsuits, divorce, former spouses, beneficiary changes, alleged undue influence, incapacity, Slayer Statute claims, estate disputes, and other contested life insurance matters.
Call 800-337-7755 or chat with our live agents today. Our firm may handle qualifying life insurance beneficiary and interpleader matters on a contingency fee basis, meaning you owe us no fees or costs unless we obtain a recovery.
